I am a research engineer and former mathematician with a passion for translating advanced mathematical and computational methods into real-world applications. My professional background spans data science, machine learning research, and quantitative analysis.
I earned my PhD in Mathematics from the University of Waterloo in 2021, and I hold both a master’s and a bachelor’s degree in Mathematics from Sharif University of Technology. My PhD research focused on stochastic optimization, while my earlier studies delved into fundamental mathematics.
Recently I have been working on generative models for combinatorial puzzles, GPU-accelerated game solving, and deep learning for option pricing. You can read more about my projects or download my CV.
Recent News & Highlights
-
Aug 2026
Released Solvable Sokoban Without a Solver via Diffusion: a 4.9M-parameter masked diffusion model that generates puzzles that are 77.4% solvable with no solver or reward in training (project page).
-
Oct 2025
Wrote lecture notes on the Basics of Reinforcement Learning.
- Aug 2025
-
Nov 2024
Generative modeling of Heston volatility surfaces with variational autoencoders.
-
Aug 2024
Implementation of deep smoothing for implied volatility surfaces.
Selected Projects
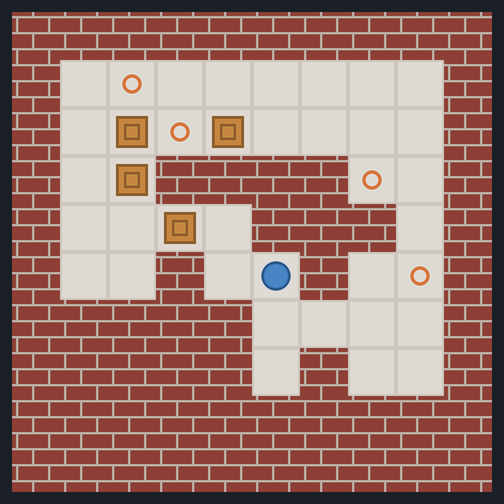
Solvable Sokoban Without a Solver via Diffusion
A masked discrete diffusion model trained only on tile completion generates Sokoban puzzles that are 77.4% solvable, and 98.7% after a single-wall repair.
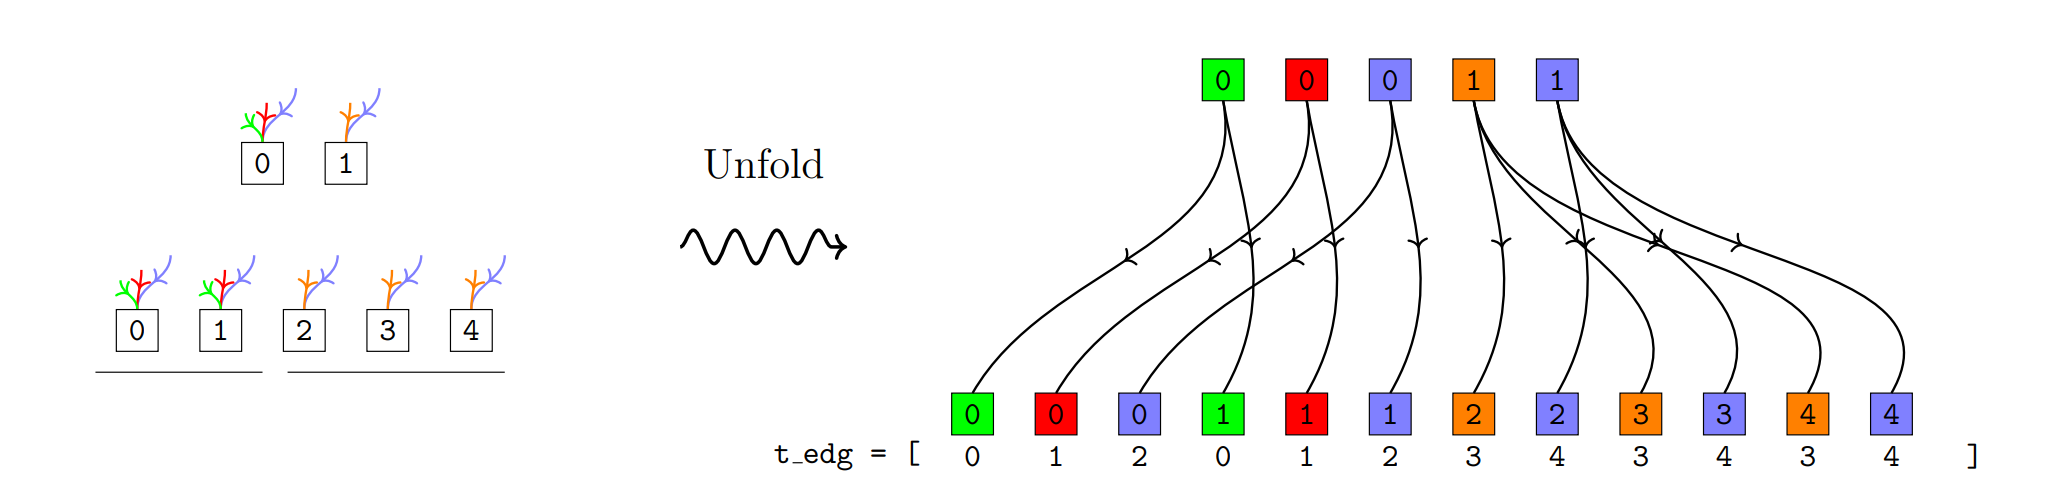
Solving Pasur Using GPU-Accelerated Counterfactual Regret Minimization
A CUDA-accelerated framework for simulating the card game Pasur and computing near-Nash equilibria with CFR.
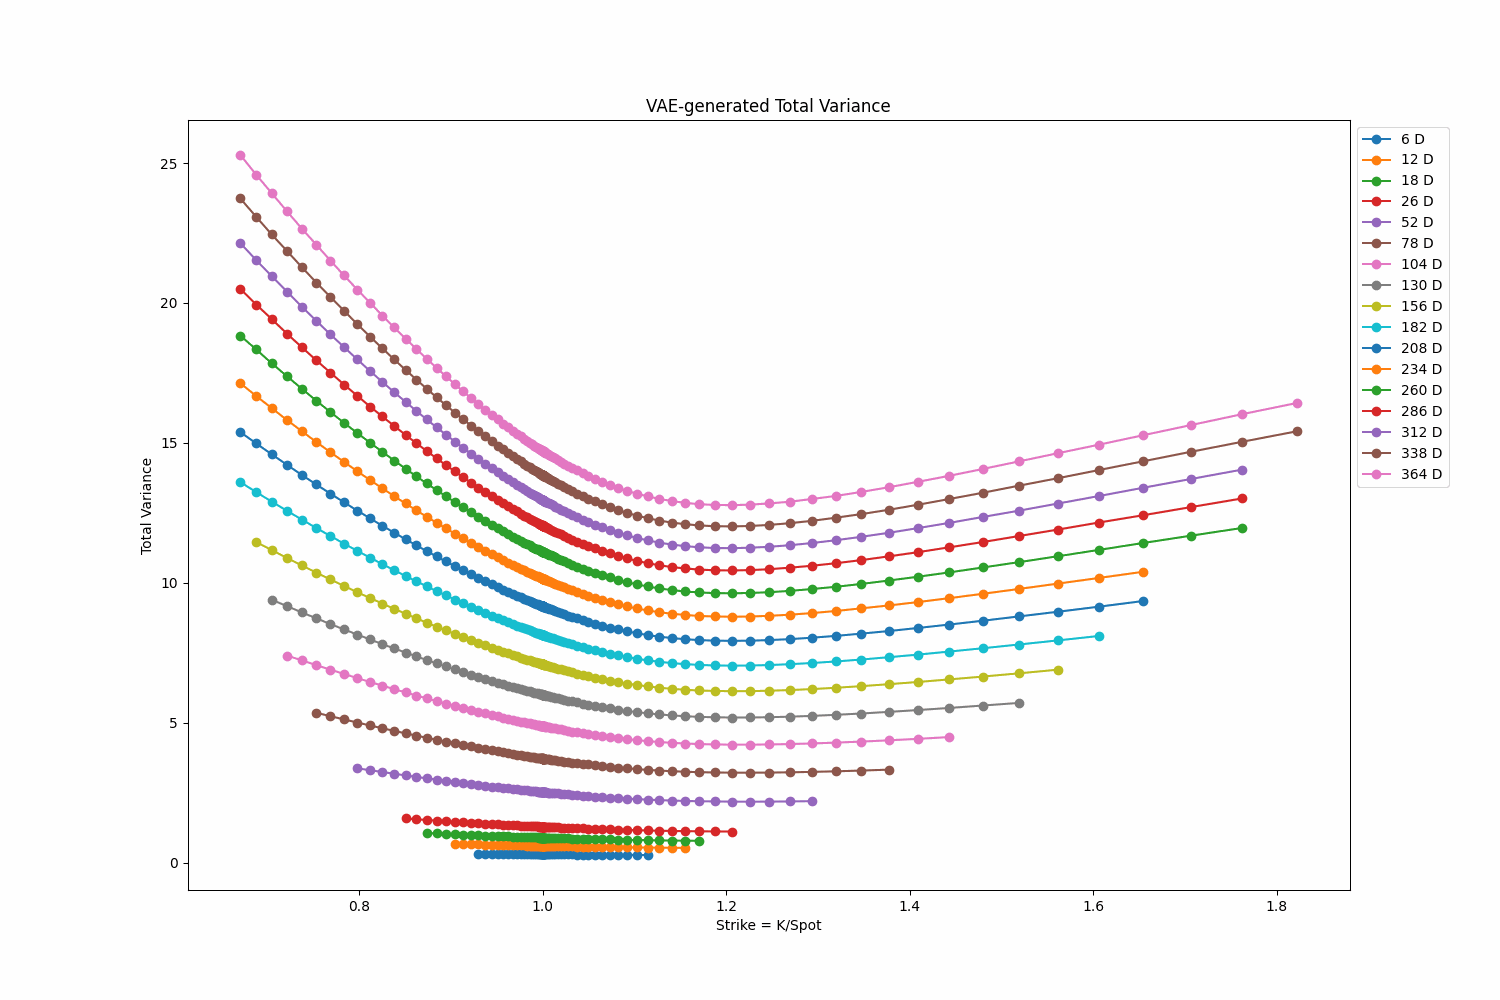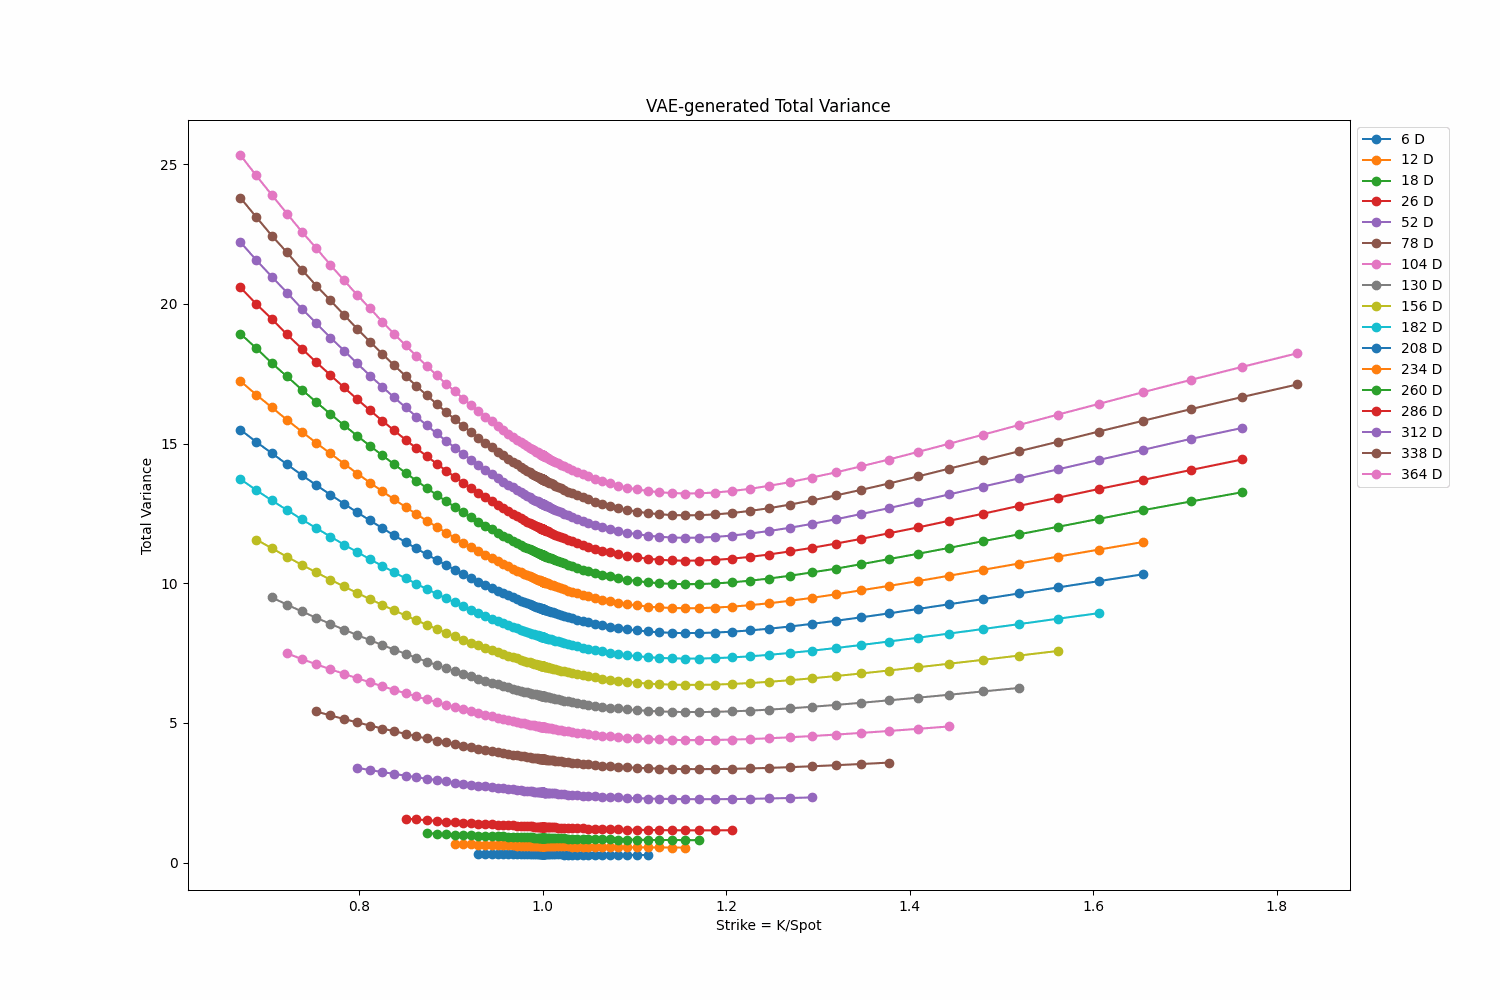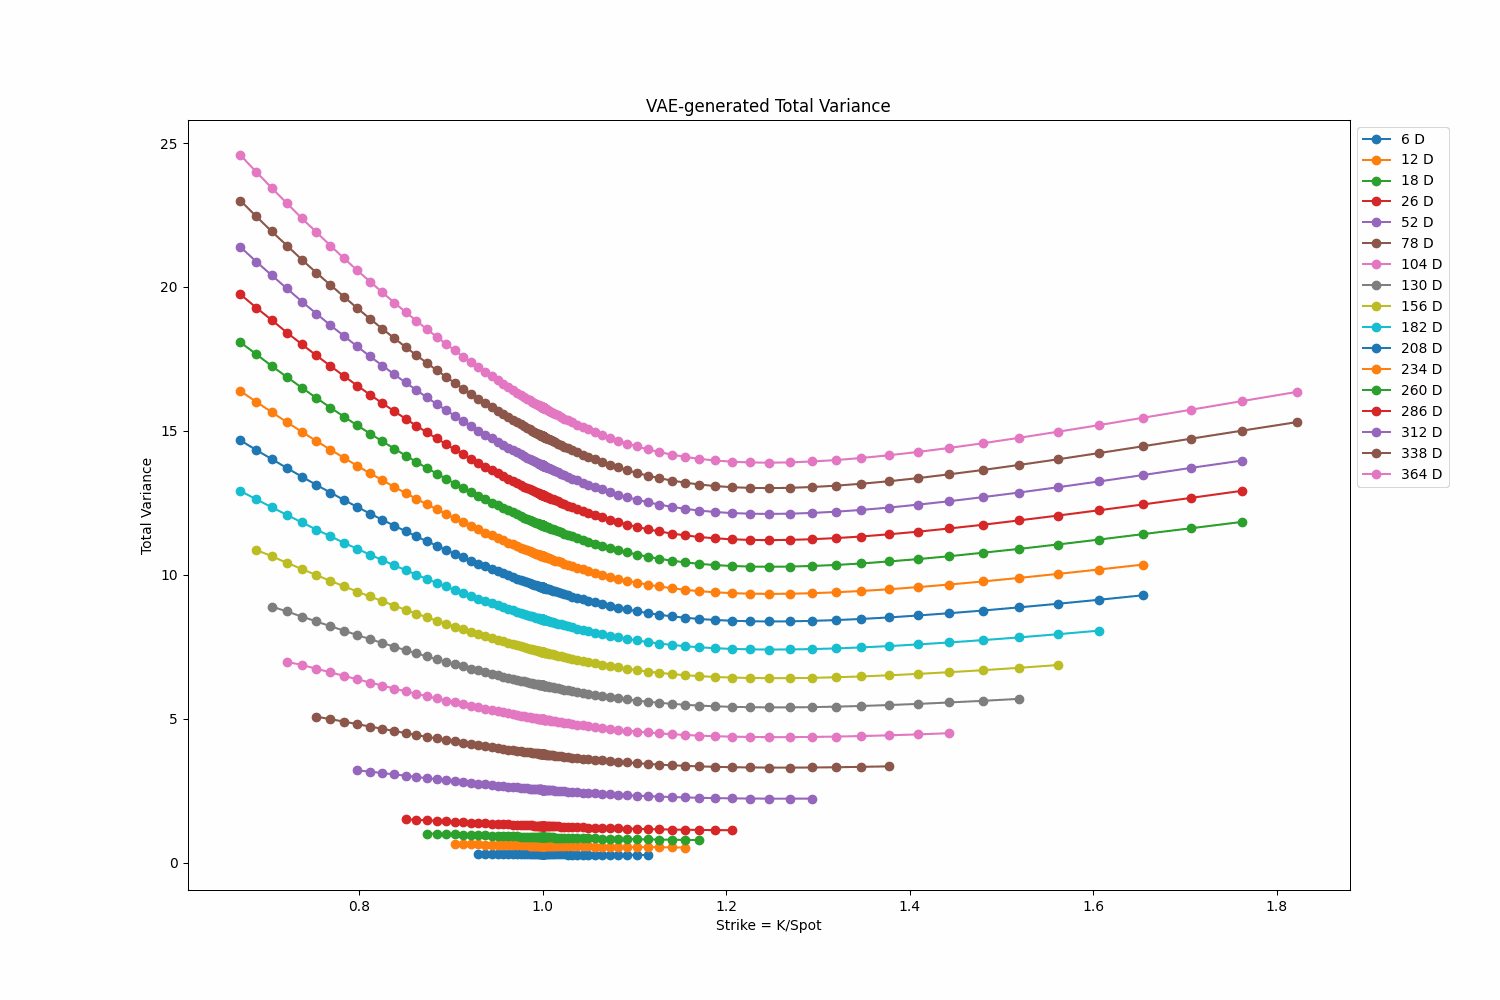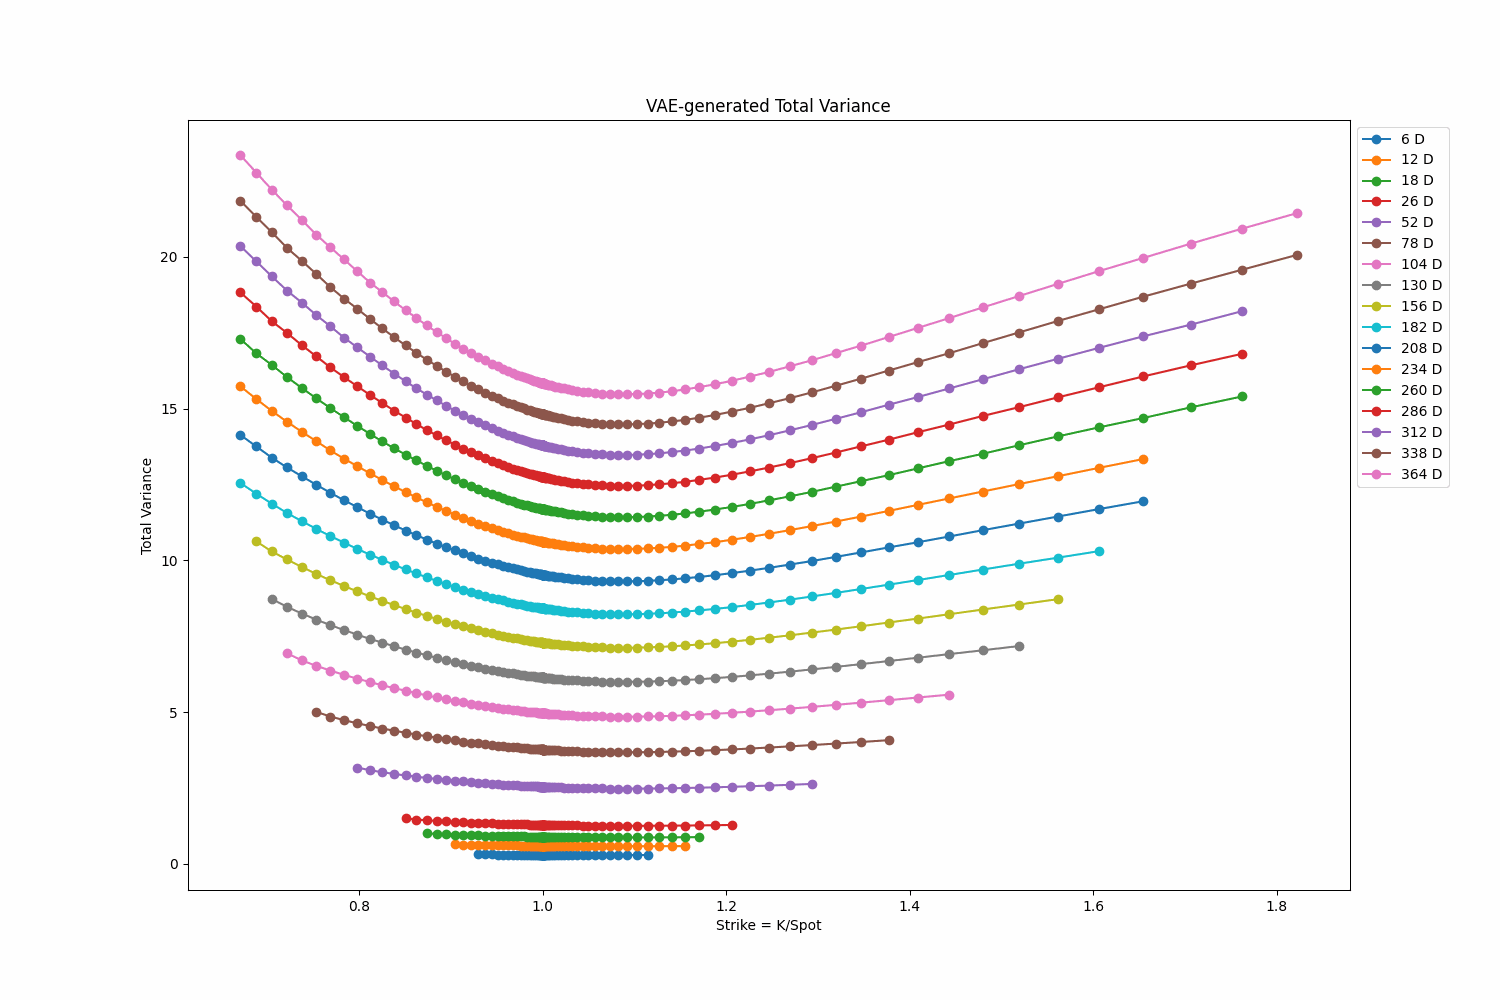
Generative Modeling of Heston Volatility Surfaces Using VAEs
A variational autoencoder that generates new Heston volatility surfaces for pricing exotic derivatives.
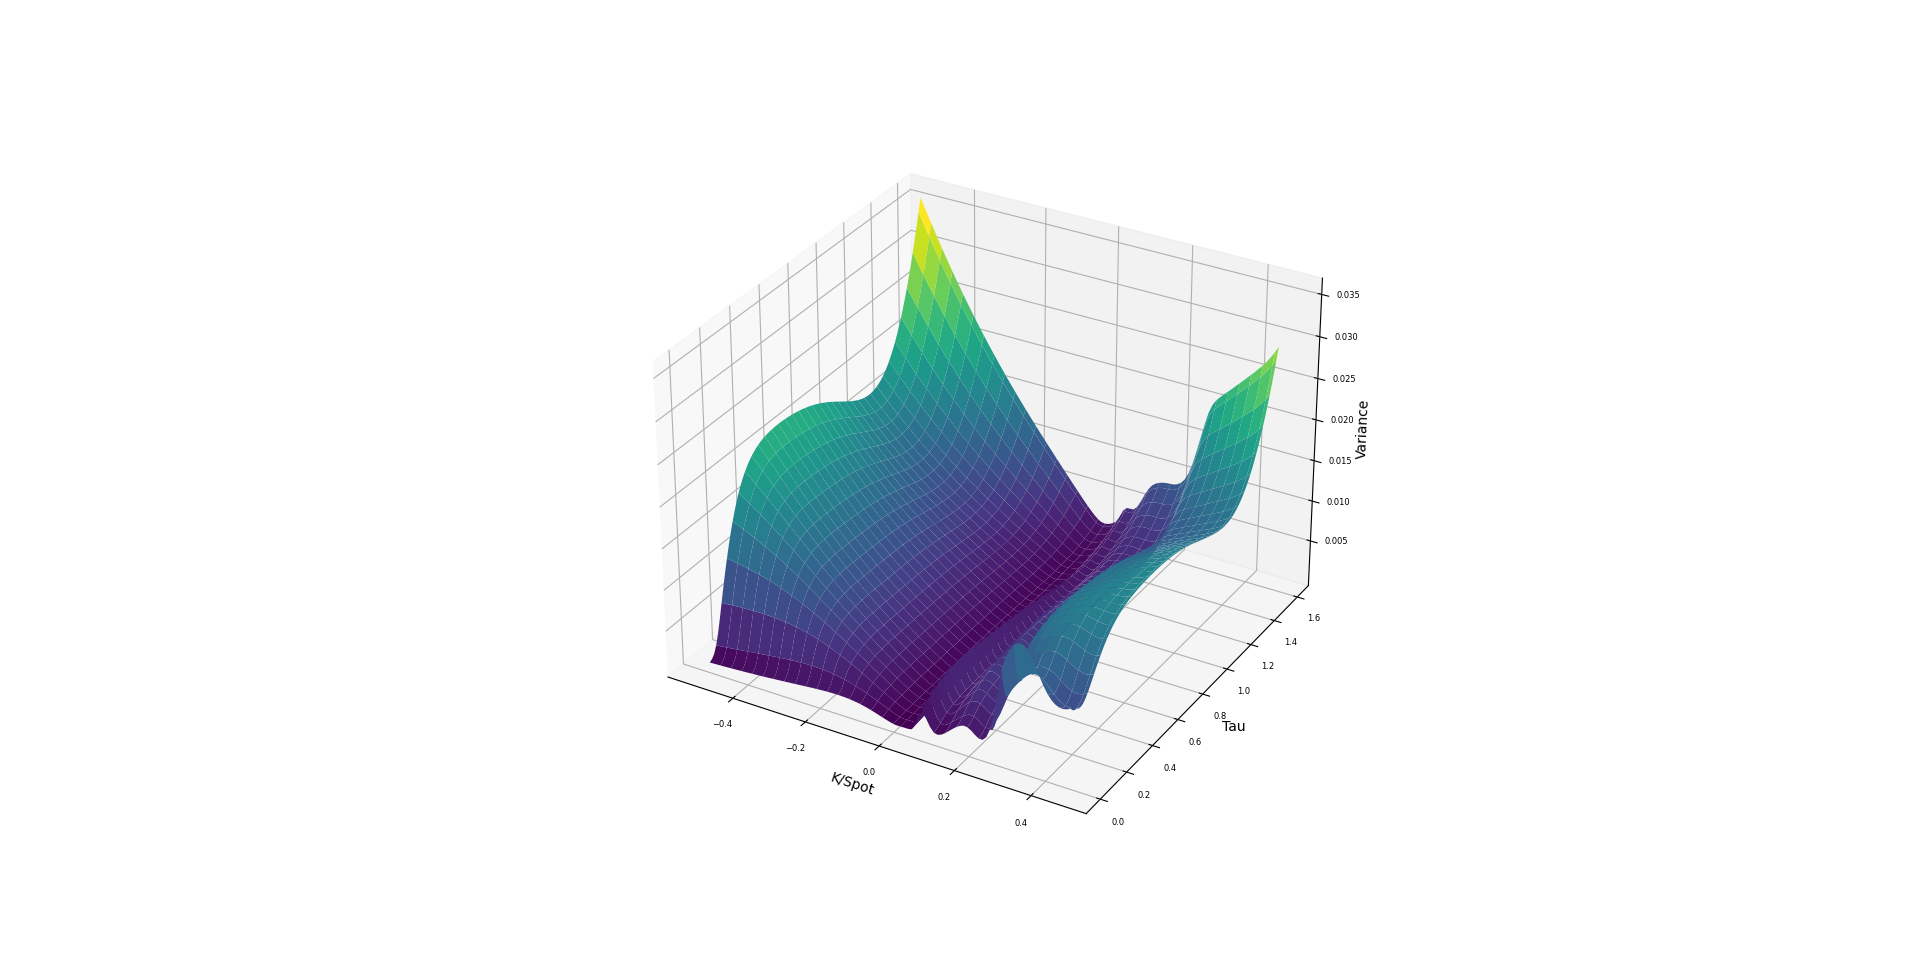
Deep Smoothing for Implied Volatility Surfaces
Neural networks that fit market data while keeping the implied volatility surface arbitrage-free.
See all projects, including my solutions to Shreve’s Stochastic Calculus for Finance II and my PhD work on SGD termination criteria, on the projects page.
Notes
- Basics of Reinforcement Learning
- Quantitative finance: Shreve solutions, Exotic Options, Feynman-Kac Theorem, Dupire’s Formula, Implied Volatility
See all of them on the notes page.